



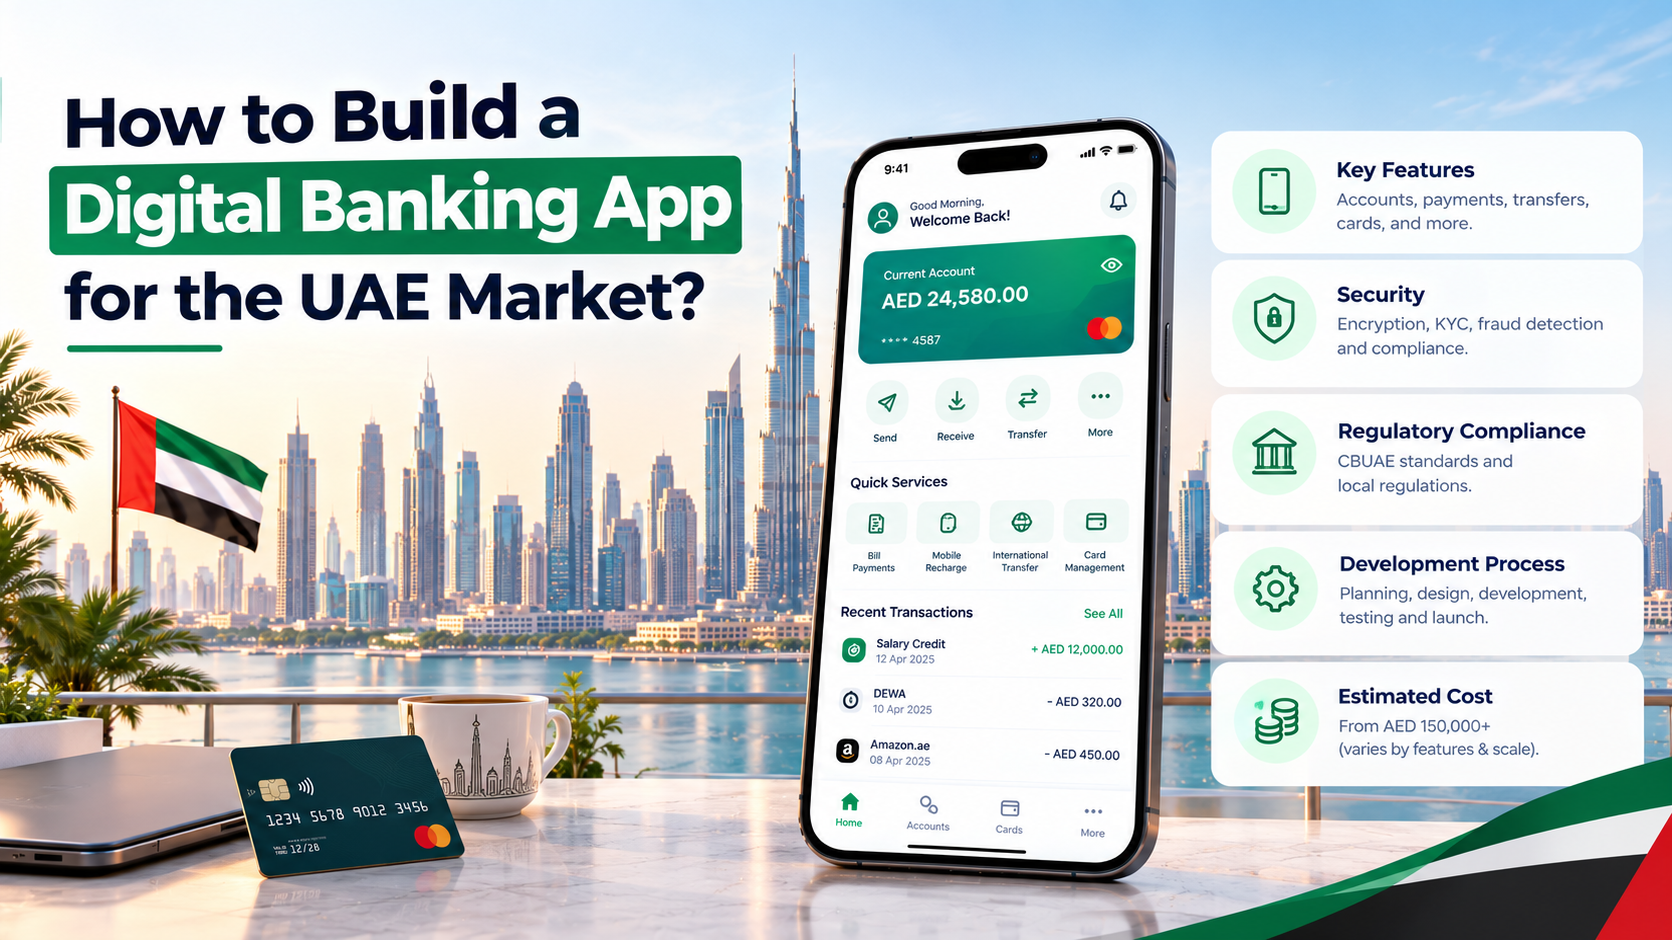
How to Build a Digital Banking App for the UAE Market?
As customers increasingly expect convenient financial services on their mobile devices, digital banking is becoming an important opportunity for banks, fintech startups, and businesses exploring financial technology. Partnering with a Banking App Development Company in Dubai can help turn a digital banking concept into a secure and user-friendly application tailored to the UAE market. From checking balances and transferring money to managing cards and receiving account alerts, a well-designed banking app can simplify everyday financial tasks while helping businesses deliver more accessible digital experiences.
However, building a digital banking app involves much more than designing an interface. Security, regulatory compliance, banking integrations, transaction reliability, and customer trust must be considered from the earliest planning stages. This guide explains how to develop a digital banking app for the UAE, including essential features, security requirements, development costs, technology choices, and the steps businesses should take before launch.
What Is a Digital Banking App?
A digital banking app allows customers to access banking services through a smartphone or other digital device. Depending on the institution and the services it is authorized to provide, an application may support account information, transfers, card management, bill payments, statements, and customer support.
Digital banking products can take several forms:
- Mobile banking apps: Applications offered by banks to help existing customers manage their accounts.
- Digital-first banking platforms: Services designed around digital customer onboarding and mobile-based interactions, subject to applicable licensing and operating arrangements.
- Business banking apps: Applications that help companies manage accounts, payments, expenses, and authorized users.
- Banking companion apps: Applications that provide financial information or connect customers to services delivered by an authorized financial institution.
The business model determines the scope of the product. An app that displays financial information through an authorized provider may have different requirements from one that initiates payments or offers regulated banking services directly.
Why Build a Digital Banking App for the UAE Market?
For financial institutions and fintech businesses, a digital banking application can provide a convenient channel for customer interactions and everyday financial activities.
Improve Customer Convenience
Customers may be able to check account information, review transactions, manage cards, and access support without visiting a physical branch for every task. Clear navigation and reliable transaction updates can make these activities easier.
Deliver Better Digital Experiences
A mobile application gives businesses an opportunity to simplify complex financial workflows. For example, customers could manage payment beneficiaries, review statements, or receive alerts through a single interface, depending on the services supported.
Support Business Banking
Small and medium-sized businesses may benefit from digital tools for payment approvals, account visibility, transaction history, and financial reporting. Business banking applications often need additional user roles and approval workflows compared with consumer apps.
Build a Scalable Digital Product
A carefully planned application can evolve through new features, integrations, and improved workflows. Businesses should design for their expected operating needs without overbuilding before validating the product.
Essential Features of a Digital Banking App
The required features depend on the institution, customer segment, and services offered. The following capabilities are common considerations when planning a digital banking product.
1. Secure Registration and Login
Customers need a reliable way to access their accounts. Depending on the service and risk level, authentication may include:
- Secure account registration
- Multi-factor authentication
- Biometric authentication supported by the device
- Password and PIN management
- Device and session management
- Secure account recovery
Customer onboarding requirements should be defined with the relevant financial institution and compliance specialists. If identity verification or customer due diligence is required, the process must be integrated appropriately.
2. Account Dashboard
The dashboard should present relevant financial information in a clear and accessible format. It may include account balances, available balances where supplied, recent transactions, account summaries, and links to frequently used functions.
The application must clearly distinguish between confirmed, pending, and failed transactions where applicable. Displayed financial data should be retrieved from authorized sources rather than relying on unverified client-side values.
3. Money Transfers and Payments
Transfer and payment capabilities may include transfers between eligible accounts, beneficiary management, bill payments, and supported domestic or international payment workflows.
The exact functionality depends on the services provided by the financial institution, the relevant payment networks, and applicable requirements. Transaction limits, fees, processing times, and status updates should be presented clearly to customers.
4. Card Management
Where supported by the issuing institution, customers may be able to view card details, freeze or unfreeze a card, manage permitted settings, and report a lost or stolen card.
Sensitive card information requires strong protection. Features should be implemented through authorized systems and follow the applicable security requirements.
5. Transaction History and Statements
Customers may need to search transactions, filter activity by date, review payment details, and download statements. These functions should be easy to navigate and should reflect the authoritative records provided by the relevant banking systems.
6. Notifications and Alerts
Notifications can inform users about payments, account activity, card changes, and important security events. Notification design should avoid exposing unnecessary sensitive information on a locked device.
7. Customer Support
A banking app should provide clear access to support. Depending on the product, this could include secure messaging, help articles, support requests, or connections to an authorized customer service team.
8. Admin and Operations Dashboard
Authorized staff may require tools to manage service requests, review operational issues, oversee user access, and monitor application performance. Access to sensitive functions should be restricted by role, with audit records for important actions.
Security Requirements for Digital Banking Apps
Security is fundamental to banking app development. A secure product requires coordinated controls across the mobile app, backend, infrastructure, external integrations, and operational processes.
Encryption and Data Protection
Sensitive information should be protected in transit and at rest using suitable encryption practices. Encryption needs to be supported by sound key management, controlled access, secure storage, and appropriate retention policies.
Strong Authentication and Authorization
Authentication establishes who is accessing an account, while authorization determines what that user can do. The app should enforce appropriate permissions and additional verification for sensitive actions where necessary.
Business banking apps may also need multiple approval levels so that one employee cannot perform every high-risk operation without authorization.
API and Backend Security
Banking apps frequently communicate with backend services and external providers. APIs should use appropriate authentication, authorization, input validation, rate limiting, and monitoring.
Sensitive credentials should not be embedded in mobile application code. Transaction processing and other critical decisions should be handled by appropriately secured backend systems.
Fraud Prevention and Monitoring
Depending on the product, risk controls may include transaction limits, suspicious activity alerts, device and session signals, and additional verification for unusual activity.
Automated fraud detection can help identify patterns that warrant investigation, but it requires careful monitoring and human oversight where appropriate. No single control can eliminate all fraud risk.
Testing and Ongoing Maintenance
Before launch, the app should undergo functional, performance, and security testing. Depending on the risk profile, testing may include dependency analysis, code review, penetration testing, and independent security assessments.
After launch, businesses need a plan for security updates, monitoring, incident response, vulnerability remediation, and periodic reviews. Banking security is an ongoing responsibility, not a one-time development milestone.
UAE Regulatory and Compliance Considerations
Digital banking is a regulated area, and requirements depend on the services offered, the legal entity providing them, and the operating structure.
Before development starts, businesses should establish whether the product will be operated by a licensed bank, developed for a regulated financial institution, or delivered in partnership with an authorized provider.
Important considerations may include:
- Applicable financial services licensing and approvals
- Customer identification and due diligence requirements
- Anti-money-laundering and sanctions controls, where applicable
- Data protection and privacy obligations
- Transaction monitoring and recordkeeping
- Payment network and third-party provider requirements
- Security, audit, and operational risk controls
Depending on the proposed activity, the relevant UAE regulatory framework may involve the Central Bank of the UAE or the regulator responsible for an applicable financial free zone. Businesses should seek qualified legal and regulatory advice to determine which requirements apply to their specific model.
Hiring a software development company does not itself authorize a business to provide banking or other regulated financial services. Compliance requirements should be addressed alongside product design and technical planning.
How Much Does Digital Banking App Development Cost in the UAE?
Development costs vary depending on the required features, integrations, security controls, platform choices, and project complexity. The following figures are broad illustrative planning estimates, not verified market quotations.
| Project Type | Indicative Development Cost |
|---|---|
| Basic banking companion or financial dashboard | $20,000–$45,000 |
| Mid-level banking app with integrations | $45,000–$100,000 |
| Advanced digital banking application | $100,000–$200,000+ |
| Complex multi-service banking platform | $200,000+ |
These estimates refer to software development planning and may not include licensing, legal advice, independent security assessments, provider onboarding, transaction charges, or ongoing operational costs. A full digital banking product connected to core banking systems can be significantly more complex than a financial information app.
What Influences the Cost?
Feature complexity: Transfers, card controls, statements, approvals, and advanced account workflows increase development and testing requirements.
Banking integrations: Connecting to core banking systems, payment providers, identity verification services, or other external platforms requires technical coordination and may involve provider fees.
Security requirements: Strong authentication, auditability, fraud controls, and independent assessments add effort but are essential for appropriate risk management.
Platform selection: Building for Android and iOS may require additional implementation and testing. Cross-platform development can share some code, but it does not remove platform-specific security and quality assurance.
Compliance-related scope: Identity verification, recordkeeping, monitoring, and reporting requirements depend on the operating model and may affect both development and operational budgets.
Maintenance and infrastructure: Hosting, monitoring, updates, customer support, and third-party service charges should be planned separately from the initial build.
Ask for a project-specific estimate that clearly separates development, integration, security testing, provider fees, and ongoing support.
Step-by-Step Process to Build a Digital Banking App
Step 1: Define the Business Model
Decide whether the app will serve individual customers, businesses, or both. Establish which financial services it will support and which organization will provide them.
Step 2: Identify Regulatory and Integration Requirements
Determine the applicable licensing and compliance obligations with qualified specialists. Identify the financial institution or authorized providers that will supply account data, payment capabilities, or other services.
Step 3: Define the MVP
An MVP should focus on the essential user journeys needed for the product to deliver value. It must still include the security and compliance controls required for its intended activities.
Step 4: Design the User Experience
Create prototypes for registration, account access, transfers, transaction confirmation, card management, and support. Test whether users can understand important information and recover safely from errors.
Step 5: Choose the Technology Stack
Select the mobile framework, backend architecture, database, hosting environment, and integration approach based on the product’s requirements. Prioritize maintainability, reliability, security, and the ability to support future changes.
Step 6: Develop and Test
Build the mobile application and backend, integrate the required systems, and test key workflows. Pay particular attention to duplicate transaction requests, interrupted connections, incorrect permissions, and inconsistent responses from external providers.
Step 7: Prepare for Launch
Complete applicable approvals, provider onboarding, security reviews, operational procedures, support workflows, and release testing. Confirm who is responsible for monitoring and maintaining the application after launch.
Step 8: Monitor and Improve
Track reliability, user feedback, failed workflows, support issues, and security alerts. Use these findings to prioritize improvements and keep the product aligned with customer and business needs.
Android vs. iOS for Banking Apps
Your target audience, budget, security requirements, and product roadmap should guide the platform decision.
An Android App Development Company can help build an Android version of your banking app, while an iOS App Development Company can develop the corresponding experience for Apple devices.
Some businesses launch on both platforms, while others consider a phased rollout. Cross-platform development can reduce duplicated implementation work, but biometric authentication, secure storage, device behaviour, notifications, and transaction workflows still need careful testing on supported devices.
The goal is to provide a consistent and secure experience across the platforms you choose to support.
How to Choose a Banking App Development Partner
Selecting the right development partner can affect the product’s reliability, maintainability, and long-term cost.
When evaluating a Mobile App Development Company in Dubai, ask how it approaches backend architecture, secure integrations, authentication, testing, deployment, and post-launch maintenance.
Review these factors before signing a contract:
- Relevant financial or sensitive-data application experience
- Technical architecture and integration planning
- Security testing and vulnerability management
- Clear project scope and delivery milestones
- Code ownership and technical documentation
- Third-party costs and external dependencies
- Maintenance, support, and incident response arrangements
A Mobile App Development Company in UAE should be able to explain how the proposed solution fits your business requirements and recognize when specialist regulatory or security advice is necessary.
When comparing a Mobile App Development Company, do not rely on price or delivery promises alone. Evaluate the proposed scope, security practices, technical approach, and responsibilities after launch.
How A2Solutions Can Help With Banking App Development
A2Solutions can be considered as a development partner for businesses planning a custom mobile financial application. The process should begin with understanding your intended users, business model, essential workflows, integrations, and technical requirements.
Depending on the project, the development scope may include mobile interfaces, backend services, account dashboards, authorized third-party integrations, administrative tools, and security-focused testing.
If you are planning a banking product for the UAE, prepare a brief describing the services your app will provide, the organization responsible for those services, the target customers, and the systems it must connect to. This helps establish a realistic scope and identify important dependencies early.
Discuss your requirements with A2Solutions to explore the appropriate development approach, project stages, and support needs for your application.
Frequently Asked Questions
How much does it cost to build a digital banking app in the UAE?
A basic banking companion or financial dashboard may cost approximately $20,000–$45,000, while a more advanced banking app may cost $100,000–$200,000 or more. The actual cost depends on features, integrations, security requirements, and project scope.
How long does it take to develop a banking app?
A focused MVP may take around three to six months, while a complex banking application may require six to twelve months or longer. These are indicative estimates. Integration dependencies, security reviews, provider onboarding, and regulatory approvals can affect the timeline.
What features should a digital banking app include?
Common features include secure login, account information, transaction history, supported transfers and payments, card management where available, notifications, customer support, and administrative tools.
Does a banking app need regulatory approval in the UAE?
The requirements depend on the activities performed and the organization operating the service. Some financial services require specific licences, approvals, or authorized partners. Businesses should obtain qualified regulatory advice before launch.
Can a startup build a digital banking app?
A startup can develop a banking-related application, but its operating model matters. Some products provide financial information or work with authorized providers, while others involve regulated activities that require appropriate permissions and arrangements.
Should I develop both Android and iOS applications?
That depends on your customers, budget, and launch strategy. You can develop both platforms together or consider a phased rollout, provided the chosen approach meets the product’s security and user requirements.
Can AI be added to a banking app?
AI can support customer service, financial insights, and fraud-risk monitoring, depending on the use case. Sensitive decisions require appropriate validation, oversight, privacy safeguards, and ongoing monitoring.
Final Thoughts
Building a digital banking app for the UAE market requires a clear business model, a reliable technical foundation, and careful attention to security and regulatory requirements. The right starting point is not a long list of features but a defined customer need and a realistic plan for delivering the required financial services.
Start by clarifying the operating model, confirming the applicable compliance requirements, and prioritizing essential user journeys. Then work with an experienced development team to define the architecture, integrations, testing strategy, budget, and ongoing support arrangements.
A well-planned banking application can give businesses a foundation for improving digital financial experiences while allowing the product to evolve responsibly as customer needs change.
Also Read:- Fintech App Development in Dubai: Features, Security & Cost
